An urgent update was sent in the existing PwC thread identifying the insolvency administrator's R33 opposition as current procedural material and explaining why PwC's 2015–2016 file may be important evidence.
27 · 09 · 2026
Protective mandate, remuneration and later relationships
Gil Marer alleges that the mandate's protective purpose was defeated and raises a possible reversal of loyalty encouraged by later economic relationships. The question requires entity, team, date, mandate, work, fee, payer, conflict and information-use evidence. The December 2014 change of billing recipient to Matkator was requested by the client and accepted by email: it does not prove a unilateral PwC change or determine the economic terms of every Sun Park engagement.
The 2016 record documents protective work, client warnings and knowledge of the client's criminal thesis. PwC's reply also explained the civil challenge it was preparing and its concern about the deadline. These records must be read together. No independent PwC finding of criminal liability against identified persons is attributed.
The RICPE first-quarter 2021 report, page 11 records PwC tax due diligence on Construcciones Acosta Matos's Merlín project. This is a specific later relationship on another project; it does not itself identify the 2016 team, precise retainer, payer or misuse of the Sun Park file. The requested investigation must test whether safeguards were preserved, abandoned or compromised and by whom.
URGENT INSTITUTIONAL UPDATE · 21–22 SEPTEMBER 2026
RPL 3304 update sent; canonical entity name corrected; documentary response remains open.
A template/transcription error was corrected: the canonical entity is Aweswell Limited; the legal-register literal is AWESWELL LIMITED, company 07716847.
A bounded mailbox review through 22 September located no substantive response. Silence is not admission and does not prove reading, acceptance, internal review or agreement.
Role boundary. PwC is addressed as a potential historical professional-record custodian and witness within its documented engagement and notice perimeter—not as a proven participant in an alleged offence. R33 is the insolvency administrator's party filing, not a judicial determination.
Finite action: preserve and identify the 2015–2016 engagement file, matter/workspace custodians, conflict and former-client searches, the Legal/Risk/Compliance trail, the exact scope of Carlos Saavedra's work, direct insolvency-administrator contacts and any later overlapping mandate or information barrier.
START HERE · CURRENT INSTITUTIONAL STATUS · 18 SEPTEMBER 2026
What is established, what is not, and what PwC can resolve from its own records.
This is the first-read route for PwC Legal, Risk, Compliance and any independent reviewer arriving from the institutional correspondence. It separates verified chronology from allegations and missing bridges before the longer evidential record below.
EstablishedPwC had substantial professional involvement before the later RICPE/Acosta period; the 2016 penal-route instruction and PwC-team acknowledgement are contemporaneous; PwC later confirmed contact with the Insolvency Administrator; and the matter was escalated through PwC UK Risk into Spain Legal/Compliance in 2021.
Not establishedThe unread 18 September burofax is not classified here as retaliation; no misuse of confidential information, conflict breach, same-asset later mandate, Sun-Park-derived fee flow, quid pro quo or individual culpability is treated as proved.
PwC can resolveExact legal entity and engagement; former-client/conflict and independence searches; DMS/workspace access; information barriers/recusals; later mandates; invoices and payer identities; and the instruction, review and authorisation chain for any new communication.
Correction rulePrimary material capable of changing the reconstruction will be incorporated with equivalent prominence. Silence is not an admission; relationship is not responsibility; evidence is the test.
18 September notice →Later PwC relationships →Finite questions →PwC countercase →Exact 18 Sep attachment →
Version control. Public stages are identifiable: 19 August institutional escalation; 1 September evidence-census closeout; 12 September later-professional-relationships enrichment; and the 18 September fresh reporting/preservation notice. The exact image sent on 18 September is retained unchanged. During the GitLab account-access interruption, GitHub is the operational working record; the public GitLab mirror can lag and is tracked for route-by-route reconciliation rather than treated as a competing source of truth.
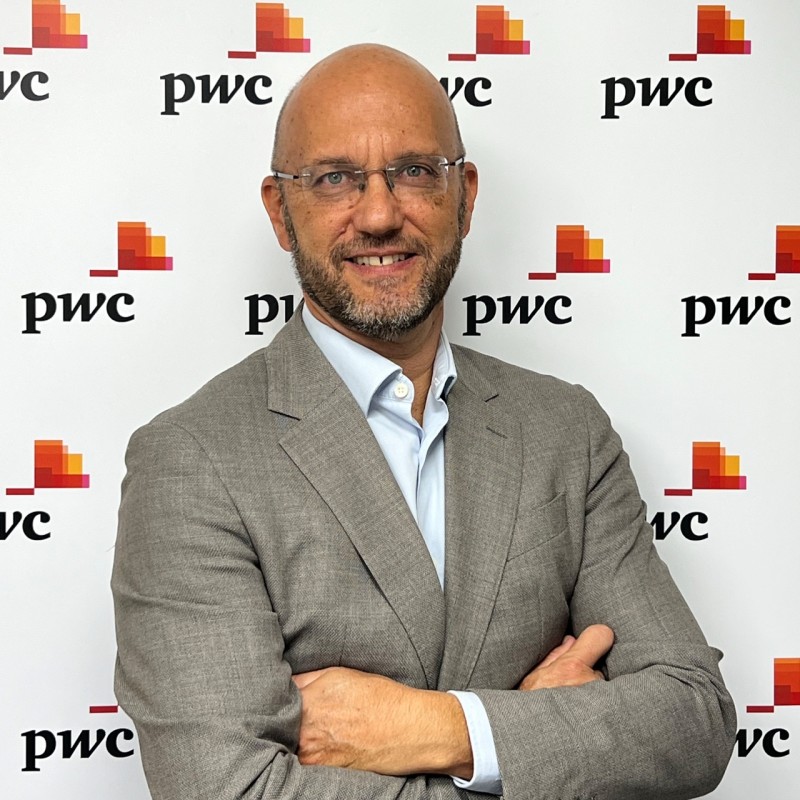
PD-SP-P-0036 · CARET_CONFIRMED · CANONICAL VISUAL ASSET
Carlos Saavedra Rodríguez del Palacio^
The exact named LinkedIn profile identifies him as a PwC national partner in Santa Cruz de Tenerife. The official PwC Spain profile confirms his full name, partner status and leadership of the Canary Islands legal practice.
^ and image boundary. The portrait and profiles reconcile identity and professional context. They do not prove conduct, a dated mandate, receipt, knowledge transfer, conflict, information use, causation, benefit, liability or wrongdoing. The image does not replace the source for any proposition.
PWC · CARLOS SAAVEDRA · PRIOR CLIENT → PENAL-ROUTE NOTICE → LATER ACOSTA/RICPE CONVERGENCE → CONFLICT RECONCILIATION
PwC knew Sun Park before the Acosta Matos / RIC Private Equity project existed.
Aweswell Limited is the UK holding company and foreign investor at the head of the relevant Spanish investment structure. The surviving record documents formal PwC Legal UK representation and intensive Landwell/PwC Canary Islands work concerning Sun Park, LPB, Matkator, Community governance, private units, alleged debt, insolvency, access and strategy.
THE CONFLICT / CONGRUENCE QUESTION
2016: detailed prior-client knowledge + an express instruction to stop the civil-only route and pursue a criminal route → later: documented PwC/Carlos professional convergence with RICPE / Grupo Acosta Matos and related hotel interests.
The central question is not whether later proximity looks uncomfortable. It is what conflict, former-client, confidentiality, independence and information-governance basis allowed any later engagement with an overlapping beneficiary/counterparty perimeter after PwC had acquired this prior client's strategic and potentially adverse information.
Precision control: the surviving July 2016 correspondence does not presently show a separate Carlos-authored acknowledgement. It shows Carlos copied on the 16 June instruction and on the 19–20 July exchange. Miguel Hernández/PwC replied: “Tomamos nota de vuestra decisión.” The safe proposition is therefore PwC-team notice, with Carlos copied, unless a further Carlos-authored source is located.
Evidence-led · maximum scrutiny · no finding of wrongdoing
Editorial boundary. This page does not state that Carlos Saavedra or PwC “switched allegiance” as a proven breach, misused confidential information, committed a deontological violation or assisted wrongdoing. It documents the chronology and asks what safeguards, conflict review and mandate boundaries existed.
1 · What Carlos/PwC knew and did in 2016
The record is not retrospective attribution of knowledge.
89.7 hPwC billing appendix records named Apr–May 2016 legal/advisory work.
26 AprCarlos recorded six hours for the Sun Park Community meeting and strategy preparation.
10 JunTwo located AMR recordings measure ≈126m36s. A later derivative transcript states 144 min; the discrepancy remains open.
Jul 2016PwC was finalising a challenge to the 26 April resolutions while the client redirected the strategy toward the penal route.
CARLOS / PWC — CONTEMPORANEOUS WORK RECORD
PwC's own appendix records Carlos coordinating the team, defining strategy, preparing for and attending the 26 April Sun Park meeting, planning strategy with Juan Tomás Parrilla and coordinating with Cuatrecasas.
LITIGATION IMPLEMENTATION · 12–16 MAY 2016
The primary chain arranges notarial appointments for general litigation powers from LPB and Simon Peter Thompson in favour of listed court agents and PwC lawyers Carlos Saavedra, Miguel Hernández and Elena Santos. This proves a concrete Community-challenge implementation track beyond meeting attendance. Without the executed instruments, the page does not claim either power was signed, accepted, used or remained in force.
REPORT + PWC TEAM · 6–10 JUN 2016
Jonathan Simó sent a report and supporting ledgers; Miguel/PwC replied “Nos parece bien. Tiremos con esta versión”. Carlos, Elena and Alejandro Perera were copied, and PwC coordinated the 10 June meeting. A same-night message said Jonathan’s report was the one taken to that meeting. This proves transmission, review, expressed approval and coordination; it does not prove reading by every copied recipient, Alejandro’s attendance, the contents of the unrecovered native v4 body, or delivery to the Administrador Concursal.
CLIENT NOTICE TO PWC · 16 JUN / 19 JUL 2016
The surviving correspondence says the client did not want further meetings with the Molina family and wanted “una querella personal”; on 19 July Patricia reiterated that “lo único que queríamos es la vía penal contra esta gente”. Carlos was copied.
PWC ACKNOWLEDGEMENT · 20 JUL 2016
Miguel Hernández/PwC replied, with Carlos copied: “Tomamos nota de vuestra decisión”, while explaining the limitation period for the civil Community challenge. This proves institutional receipt/acknowledgement by the PwC team; it should not be misquoted as a separate statement authored by Carlos.
2 · A single 2016 sequence
The instructions, legal response and insolvency contact must be read together.
Community meeting
Carlos, Miguel and Elena appear in the private-owner / Community workstream. PwC billing records strategy and attendance.
Challenges + litigation powers
PwC develops general litigation powers for LPB and Simon Thompson naming Carlos, Miguel and Elena among the lawyers. The record proves preparation, not execution.
Report + meeting + change of route
Jonathan sends the report and ledgers; Miguel/PwC approves proceeding with the version, with Carlos, Elena and Alejandro copied. PwC coordinates the 10 June professional meeting, which addresses the economic/legal architecture. On 16 June the client directs PwC to put the then document aside and pursue a personal criminal complaint rather than further meetings. The inherited “11-Jun” route is retained only as a version-history alias.
Penal route expressly reiterated
PwC says it is finalising the 26 April challenge. Patricia replies that the desired route is penal. Miguel/PwC answers that the decision is noted. Carlos is copied throughout the material exchange.
Direct AC contact
Surviving correspondence records PwC having spoken directly with the Administrador Concursal about the proposed operator/new exploitation-contract route; Patricia then asks for a written account of what was said and answered.
Protective-shield question: once PwC knew the client was characterising the conduct as potentially criminal and asking for the penal route, what risks did PwC identify, escalate, refer, preserve or decline—and where is the professional record of that decision?
3 · Later PwC relationships · entity-by-entity proof table
The later relationship is documented. The same-asset mandate, information flow and economic bridge remain separate questions.
| Date | Exact PwC entity / person | Client / project | Primary-source layer | What it proves | What it does not prove |
|---|---|---|---|---|---|
| 2019 | PricewaterhouseCoopers Auditores, S.L. | RIC Private Equity | RICPE/CNMV audit history | A formal PwC audit relationship with RICPE for FY2019. | That Carlos/Landwell worked on Sun Park, that the auditor validated Sun Park title, or that former-client information was used. |
| 4 Jun 2020 | PricewaterhouseCoopers Auditores, S.L. | RICPE; investor material also carried the Sun Park / Acosta Matos project | RICPE investor material | PwC's audit role and the Sun Park project coexisted within the same RICPE investor ecosystem. | A Sun Park engagement by PwC, validation of ownership/title, or knowledge by every PwC team. |
| Mar 2021 | PwC — exact engagement entity/team to be produced | Project Merlin / Construcciones Acosta Matos | RICPE public report states PwC began fiscal due diligence | A later PwC professional mandate for CAMSA on another project. | Identity of the 2016 Sun Park team, a Sun Park mandate, use of former-client information, or conflict breach. |
| 2021–2022 publications | Enrique Guerra — exact PwC entity/capacity requires engagement records | RICPE / PwC professional overlap | RICPE publications described Guerra as PwC adviser/Off Counsel while holding RICPE roles; RICPE's current biography describes the PwC role as former | A dated professional-role overlap that warrants exact-entity, client, mandate, chronology and independence verification. | Transfer of Carlos Saavedra's 2016 knowledge to Guerra, collective PwC knowledge, or proof that PwC performed every review attributed to it. |
| 1–5 Mar 2021 | PwC UK Risk / PwC Spain Legal & Compliance | Sun Park / RICPE complaint | Direct PwC correspondence | Institutional notice reached UK Risk and Spain's Deputy General Counsel / Chief Compliance Officer channel. | What internal checks were actually run, who accessed historic files, or what later engagement screening occurred. |
| 2022–2024 | Carlos Saavedra / PwC public professional environment | RICPE / MYND / Grupo Acosta Matos-related professional settings | Public event material | Documented later professional proximity involving Carlos personally. | A same-asset mandate, adverse retainer, confidential-information transfer, disloyalty or liability. |
| 2026 | Carlos Saavedra; Socios Inversores Canarios, S.L. | Board perimeter including Grupo Acosta Matos represented by José Daniel Acosta Matos | BORME / corporate record | A later formal professional/governance convergence capable of documentary verification. | That the role concerns Sun Park, that any fee derives from Sun Park value, or any quid pro quo. |
Economic-benefit boundary. A later professional relationship is not a traced payment flow. The present public record does not contain PwC's complete later invoices, payer records, bank records or source-of-funds tracing. Those records are requested precisely because they can prove or disprove the alleged economic bridge.
INSTITUTIONAL WARNING TRAIL · UK RISK → SPAIN LEGAL/COMPLIANCE → OGC
Receipt is not the open question; the open question is what internal review followed.
| Date | Documented PwC channel | What the surviving correspondence records |
|---|---|---|
| 1 Mar 2021 | PwC UK · Regulatory & Commercial Disputes / Risk | Polly Miles confirmed that, after speaking with Gil Marer, she escalated the concerns to PwC's Head of Risk Management. |
| 5 Mar 2021 | PwC Spain · Deputy General Counsel + Chief Compliance Officer | Pablo Fernández Guerra said the PwC Network had passed him the Canary Islands / Sun Park complaint and proposed a call with Carlos del Cubo. |
| 8 Mar 2021 | PwC Spain Legal/Compliance + UK recipients | The channel received the Sun Park/RICPE package, including the CNMV complaint and related investor/project material. |
| 2023 | PwC UK OGC | The public GitLab mirror records a later OGC handoff summarising the allegation themes and requesting the underlying correspondence; exact internal conclusions remain unproduced. |
Boundary. This proves institutional routing and sustained notice, not the content or outcome of PwC's internal investigation. The finite request remains the internal review, preservation, access, conflict, engagement-screening and decision record.
FAIR COUNTERCASE · WHAT THE INTERNAL RECORD MAY SHOW
An innocent PwC explanation is capable of documentary proof.
The outstanding records may show that later events belonged to legally distinct PwC firms, separate teams and unrelated assets; that effective former-client/conflict and independence checks were run; that historic Sun Park files were appropriately restricted; that information barriers or recusals operated; that no Sun Park confidential information was transmitted or used; that no later Sun Park mandate or Sun-Park-derived remuneration existed; and that the electronic burofax had an independently justified purpose fixed before the 18 September notice.
Why this matters. Those are not concessions or presumptions. They are falsifiable explanations. The purpose of the preservation and finite-document request is to allow PwC's primary records to establish them if they are true.
4 · Why the sequence creates a concrete conflict problem
Earlier adverse information and later professional opportunity cannot be analysed in separate boxes.
FORMER-CLIENT / CONFIDENTIALITY
What information remained protected?
PwC had access to strategy, Community positions, private-owner issues, title/deed questions, insolvency context, alleged debt, access and governance. Which of that information remained confidential and relevant when later Acosta/RICPE-related matters were considered?
CONFLICT ACCEPTANCE
On what basis was later work accepted?
What conflict search, connected-party mapping, informed consent or waiver, PwC Legal/Risk review, independence analysis or recusal was completed before any later overlapping engagement?
INFORMATION BARRIERS
Were the earlier files isolated?
Which PwC systems retained the 2016 files; who could access them; what matter-opening searches surfaced them; and what information barriers or access controls were created?
CROSS-ASSET CONGRUENCE
Is this one isolated overlap or a recurring professional relationship?
Where Carlos/PwC later worked with the Acosta Matos/private-equity perimeter on other hotel assets, the repository should map each engagement by date, PwC legal entity, client, asset, role and fee/appointment status. Repetition may strengthen the relevance of the conflict inquiry, but it is not itself proof of a breach.
The question PwC should be able to answer directly: after the 2016 Sun Park team had received the client's express penal-route instruction and accumulated detailed strategic information, on what documented conflict-management basis was later professional work with the overlapping Acosta Matos / RICPE private-equity perimeter accepted, and what safeguards protected the former client's information and interests?
5 · Congruence matrix to be maintained in the repository
Every later overlap should be tested, not merely described.
| Dimension | Required repository test |
|---|---|
| Person / PwC entity | Carlos personally, Landwell/PwC Tax & Legal, PwC Auditores or another member firm? Do not collapse distinct legal entities. |
| Earlier information | What Sun Park/Aweswell/LPB/Matkator information was actually received, created or accessible in 2016? |
| Later client/perimeter | RICPE, CAM/Grupo Acosta Matos, HNT, MYND, Canarian Hospitality or another connected party? |
| Asset overlap | Sun Park itself, another Acosta hotel asset, or a wider investment vehicle? |
| Role / mandate | Audit, legal, tax, transaction, finance, governance, company-secretarial, public-funds or other advisory role? |
| Conflict controls | Conflict search, Legal/Risk clearance, independence review, informed consent/waiver, information barrier, recusal and DMS access controls? |
| Evidence status | Verified primary record, public record, institutional statement, inference, open question or evidence gap. |
Publication rule: do not use “switched allegiance” as an established fact unless a later adverse mandate and the legally relevant conflict are proved. The public formulation is later professional convergence creating a documented former-client/conflict question.
6 · Six finite questions for PwC Legal, Risk and leadership
1 · 2016 notice and response
What did PwC understand from the 16 June and 19 July instructions to move to a criminal route, and what advice, referral, escalation or closure decision followed?
2 · Subsequent mandates
Did Carlos or any PwC entity later accept work for RICPE, Grupo/Construcciones Acosta Matos, HNT, MYND, Canarian Hospitality or connected interests, on Sun Park or other assets?
3 · Conflict review
For each such mandate, what former-client, connected-party, confidentiality, independence and conflict analysis was performed?
4 · Consent and barriers
Was any informed consent/waiver sought, and what information barriers, recusal or access restrictions were implemented?
5 · Same people / systems
Which professionals or systems connected the 2016 files to later matters, and did conflict/KYC searches surface Aweswell, LPB, Matkator, Sun Park or the relevant individuals?
6 · Other assets
What later professional work did Carlos/PwC undertake with the same Acosta Matos/private-equity perimeter on other hotel or investment assets, and how was the cumulative conflict analysis documented?
7 · CNMV and public-funds control
Do not manufacture unsupported bridges.
CNMV: the available supervisory record does not establish that CNMV contacted PwC or any auditor, that PwC responded to CNMV, or that CNMV relied on PwC to clear Sun Park. Those remain verification questions.
Public support: if any PwC entity performed audit, legal, tax, financial, due-diligence, assurance or certification work concerning Sun Park/MYND Yaiza in RIC, regional-incentive, FEDER or other public-funding processes, identify the exact entity, mandate, dates and outputs. No such role is asserted here without source support.
8 · OPEN QUESTION TO THE ADMINISTRACIÓN CONCURSAL, FISCALÍA AND THE CONCURSO COURT
Why was Carlos Saavedra's evidence not heard at the vista de calificación?
MISSING-WITNESS / EVIDENTIAL-COMPLETENESS QUESTION
Carlos Saavedra was a documented custodian of contemporaneous evidence potentially relevant to allegations of criminal conduct, third-party responsibility, the Administrador Concursal's own knowledge and alternative causation within the concurso. The surviving 2016 record places PwC inside the legal response, records direct notice of allegations regarded by the client as potentially criminal, an express request for the penal route, and PwC contact with the Administrador Concursal.
The finite question: if Carlos was proposed, admitted, summoned, expected or otherwise positioned to give evidence in the calificación proceedings but his testimony was ultimately not heard, who requested, agreed to, acquiesced in or otherwise caused that procedural outcome, on what basis, and where is the documentary record explaining it?
TO THE ADMINISTRACIÓN CONCURSAL
What did the AC know and how was Carlos's evidence assessed?
When preparing or maintaining the calificación case, did the AC know that Carlos/PwC held this contemporaneous body of evidence? What assessment was made of its relevance to disputed Community debt, governance, access/control, third-party conduct, alternative causation and the AC's own prior knowledge?
TO FISCALÍA
Was the complete 2016 PwC chain before the prosecutor?
Before Carlos's testimony was not heard, was Fiscalía informed of the June–September 2016 evidence chain: direct notice to PwC, the express penal-route instruction and the confirmed PwC–AC contact? If not, why not; if yes, what assessment was made of its relevance?
TO THE CONCURSO COURT
What procedural decision caused the testimony not to be practised?
What judicial or procedural act resulted in Carlos not testifying? Who requested or supported that outcome, and what reasons were recorded for treating the evidence as unnecessary, inadmissible, withdrawn, waived, duplicative or otherwise dispensable?
TO ALL THREE INSTITUTIONS
What was the effect on the completeness of the calificación?
What consideration was given to whether Carlos could provide material evidence concerning conduct by actors other than the debtor's directors, the Administrador Concursal's own knowledge, the origin and treatment of disputed Community debt, and alternative explanations for deterioration, loss or displacement of the estate?
Precision control: this page does not state that the judge, Fiscalía or Administración Concursal deliberately suppressed Carlos's evidence, nor that his later PwC/Acosta/RICPE convergence explains why he did not testify. Those propositions require actor-specific proof of the procedural decision and motive. The public demand is for the record: who caused the non-practice, why, what was known at the time, and what evidence was thereby lost?
Further open question: did the court, Fiscalía or AC know of or later consider Carlos/PwC's documented professional convergence with the RICPE / Acosta Matos perimeter, and if so what relevance—if any—was attributed to it when evaluating his evidential position, independence, credibility or the completeness of the calificación record?
9 · Preservation
The conflict and missing-witness questions are capable of documentary resolution.
Por Derecho asks PwC to preserve engagement letters, KYC/client-acceptance records, conflict and independence searches, matter opening/closure records, DMS/workspace access logs, correspondence, calendars, time records, advice/drafts, 2016 criminal-route/referral material, AC-facing material, 2021 Legal/Risk escalation records, information-barrier decisions and later CAM/RICPE/HNT/MYND/Acosta work product across relevant PwC entities. The procedural record should likewise preserve the witness proposal, admission or inadmission order, summons, any withdrawal/renunciation/substitution, vista recording and minutes, party submissions, Fiscalía position, AC position and the exact act by which Carlos's testimony was not heard.
Preservation is requested because these records can resolve finite questions; it is not evidence of wrongdoing.
MULTIYEAR CLIENT-SIDE CONTINUITY · 2016–2026
Canary Islands work, separate UK legal representation, institutional escalation and later approaches remain distinct but connected tracks.
| Date | Track | Source-safe finding | Boundary |
|---|---|---|---|
| Jul–Aug 2016 | PwC Legal UK | Correspondence records UK legal advice and a 1 August invoice, including settlement from funds held in trust. | A separate UK legal-services relationship; it is not merged with the PwC Canarias mandate or later RICPE work. |
| Mar–Apr 2021 | UK Risk → Spain Legal/Compliance | Andrea Holder routed the matter to Polly Miles; Miles recorded escalation to the Head of Risk Management before the Spain channel followed. | Institutional routing, not a merits determination or proof of receipt by every copied person. |
| 2023 | PwC UK OGC | Later correspondence records OGC routing, calls and a request for underlying correspondence. | No internal conclusion or complete knowledge-transfer map is inferred. |
| 15–16 Aug 2024 | UK “new matter” | A separately presented hotel-transaction matter led to calls with the UK Real Estate Legal leader and a referral to a real-estate-finance partner. | Approach, calls and referral only—not acceptance, retainer, conflict clearance, work performed or a Sun Park/same-asset link. |
| 18 Sep 2026 | Fresh notice | The sent record is verified; one copied address produced a delivery failure. | Dispatch is not proof of delivery, reading or substantive receipt by any other addressee. |
Cross-track reading. These client-side contacts are relevant to institutional continuity, but they do not establish collective PwC knowledge, a later overlapping mandate, misuse of information, conflict breach or wrongdoing. The RICPE/Sun Park dossier, Acosta Matos perimeter, 2016 meeting record and Cuatrecasas–RAUDA track supply the connected but separately tested contexts.
10 · ^ register · people, entities, events and evidence
The finite first-hop census is complete; total identity reconciliation is not.
PARTIAL — NOT ALL IS^
What ^ means: it confirms a reconciled identity only. It does not prove conduct, dated capacity, mandate, knowledge, conflict, information use, causation, benefit, liability or wrongdoing. Events and evidence are registered and interlinked but do not receive ^.
32/35identities confirmed
3identities pending
24events registered
23evidence records
Reconciled people
- Gil Marer^
- Patricia Domínguez^
- Francisco Mario Matos Matas^
- Francisco de Borja Rodríguez-Batllori Laffitte^
- José Daniel Acosta Matos^
- Francisco Luis Molina Molina^
- Carlos Saavedra Rodríguez del Palacio^
- Miguel Hernández Lorenzo^
- Elena Santos Ramos^
- Alejandro Perera González^
- Jonathan Simó Morales^
- Simon Peter Thompson^
- Juan Tomás Parrilla Suárez^
Confirmed entities, structures, institutions and proceeding
- Aweswell Limited^
- Luchy Playa Blanca, S.L.U.^
- Matkator, S.L.U.^
- Comunidad de Propietarios Sun Park^
- Comunidad de Explotación Sun Park^
- Construcciones Acosta Matos, S.A.^
- Hotel New Trend, S.L.^
- Canarian Hospitality, S.L.^
- RIC Private Equity Investment Partners SCR, S.A.^
- MYND Yaiza^
- Cuatrecasas, Gonçalves Pereira, S.L.P.^
- Landwell-PricewaterhouseCoopers Tax & Legal Services, S.L.^
- PricewaterhouseCoopers Auditores, S.L.^
- Grupo Acosta Matos, S.L.^
- Socios Inversores Canarios, S.L.^
- Commercial Court No. 1^
- Ministerio Fiscal / Fiscalía^
- Comisión Nacional del Mercado de Valores^
- Insolvency 36/2012 — LPB^
Pending — no ^: The controlled PwC Canary Islands perimeter; the PwC UK Legal/Risk channel; and the PwC Spain Legal/General Counsel channel. The exact legal/audit firms and similarly named companies remain separate; each pending object retains its specific required source in the census.
Interlinked events and evidence
| Date | Event / evidence | Access and boundary |
|---|---|---|
| 24 Nov 2014 | PwC/Landwell proposal: client and team | Private primary source; source-safe summary without exposing its locator. |
| 31 Aug / 8 Sep 2015 | Registry appointment of Carlos-Gabriel Saavedra as attorney-in-fact of Landwell/PwC | Official BORME. This proves registered identity/capacity, not the scope of a Sun Park engagement. |
| 21–26 Apr 2016 | Engagement email, time appendix and meeting | 21 April evidence · 26 April event room. |
| 12–16 May 2016 | LPB and Simon Thompson Community challenges and litigation powers naming Carlos, Miguel and Elena | Private primary chain; it proves instructions/preparation, not execution, acceptance, use or continuing force of either power. |
| 6–10 Jun 2016 | Jonathan Simó transmits the report; PwC reviews/approves the version and coordinates the 10 June meeting | Private primary chain + canonical 10 June event · derivative transcript. Alejandro was copied; that does not prove authorship or attendance. The two AMRs measure ≈126m36s and the derivative states 144 min. |
| 12–16 Jun 2016 | Direct notice, invoice/appendix and penal-route instruction | Private primary sources; authorship and copy recipients remain separate. |
| 19–20 Jul 2016 | Penal route reiterated and “Tomamos nota” reply | The reply is attributed to Miguel/PwC; Carlos is copied. |
| 12 Sep 2016 | General PwC–insolvency-administrator contact | No detailed contracts, report or oral content is inferred. |
| 2019–2020 | RICPE audit history, Sun Park/CAM brochure and due-diligence event | RICPE dossier. Auditor presence is not project or brochure approval. |
| Mar–Apr 2021 | Institutional PwC Legal/Risk escalation | Does not prove personal receipt by Carlos; the exact internal map remains missing. |
| 1 Aug 2016 | Separate PwC Legal UK advice/invoice relationship | Private primary correspondence; distinct from the Canary Islands mandate and no later RICPE work is inferred. |
| 2023 | PwC UK OGC routing and call channel | Proves institutional routing and a request for underlying material, not an internal conclusion. |
| 15–16 Aug 2024 | Separately presented UK hotel-transaction “new matter” | Proves approach, calls and referral; not acceptance, retainer, conflict clearance, work performed or a Sun Park link. |
| 18 Sep 2026 | Fresh notice and delivery-status exception | Sent record verified; one copied address failed. No delivery/read inference for other addressees. |
| 22 Jan 2026 | CNMV response separately registered | Controlled institutional source; its content is not extended and no PwC contact or reliance is inferred. Official RICPE/auditor register. |
| 2022–2026 | Professional event and BORME corporate convergence | Acosta Matos perimeter. Formal proximity does not prove a Sun Park mandate, reward or quid pro quo. |
Decisive gaps: the exact entity/capacity of the PwC Canary Islands perimeter and the two 2021 PwC channels; executed litigation powers; the native Jonathan report v4 body and proof of delivery to the AC; engagement, conflict/independence and information-barrier records; the procedural act concerning Carlos's unpractised evidence; and full audio authentication/alignment remain missing. The page therefore does not publish an “ALL IS^” certification.
11 · 18 SEPTEMBER 2026 · FRESH REPORTING / PRESERVATION NOTICE
Electronic burofax notification received; its contents had not been retrieved when PwC was put on fresh notice.
On 18 September 2026, an automated electronic notification identified Pablo Fernández Guerra / PricewaterhouseCoopers Tax & Legal, S.L. as the sender of an electronic burofax to Gil Marer. When the follow-up institutional email was sent, the burofax had not been opened, accepted, rejected or retrieved. Its contents were therefore unknown. This record does not characterise the unread document as a threat, retaliation or legal action.
Verified transmission
At 12:10 local time, a fresh reporting/whistleblower communication and preservation notice was sent from the authenticated Monterecco mailbox. The sent copy was verified. It asks PwC to authenticate the electronic notification and, if genuine, to provide the communication through the established email channel where possible.
Madrid · London · Global copied-address list
Principal recipients: Pablo Fernández Guerra and Carlos del Cubo. The copied-address list named Gonzalo Sánchez, Carlos Saavedra, Alison Statham, Gillian Lord, Marco Amitrano, Polly Miles, Agnes Quashie and Suzanne Nethaway. A delivery-status notification records that the address used for Agnes Quashie failed. Inclusion in the list—and the absence of another bounce—does not prove delivery, reading or substantive receipt. Private email addresses are not republished.
Review before any fresh step
The notice leaves the decision entirely to PwC while inviting Spain Legal/Compliance and relevant UK/Global Legal functions to review the unread communication before any later re-notification, reissue or insistence on delivery. It does not demand withdrawal and does not prejudge the burofax.
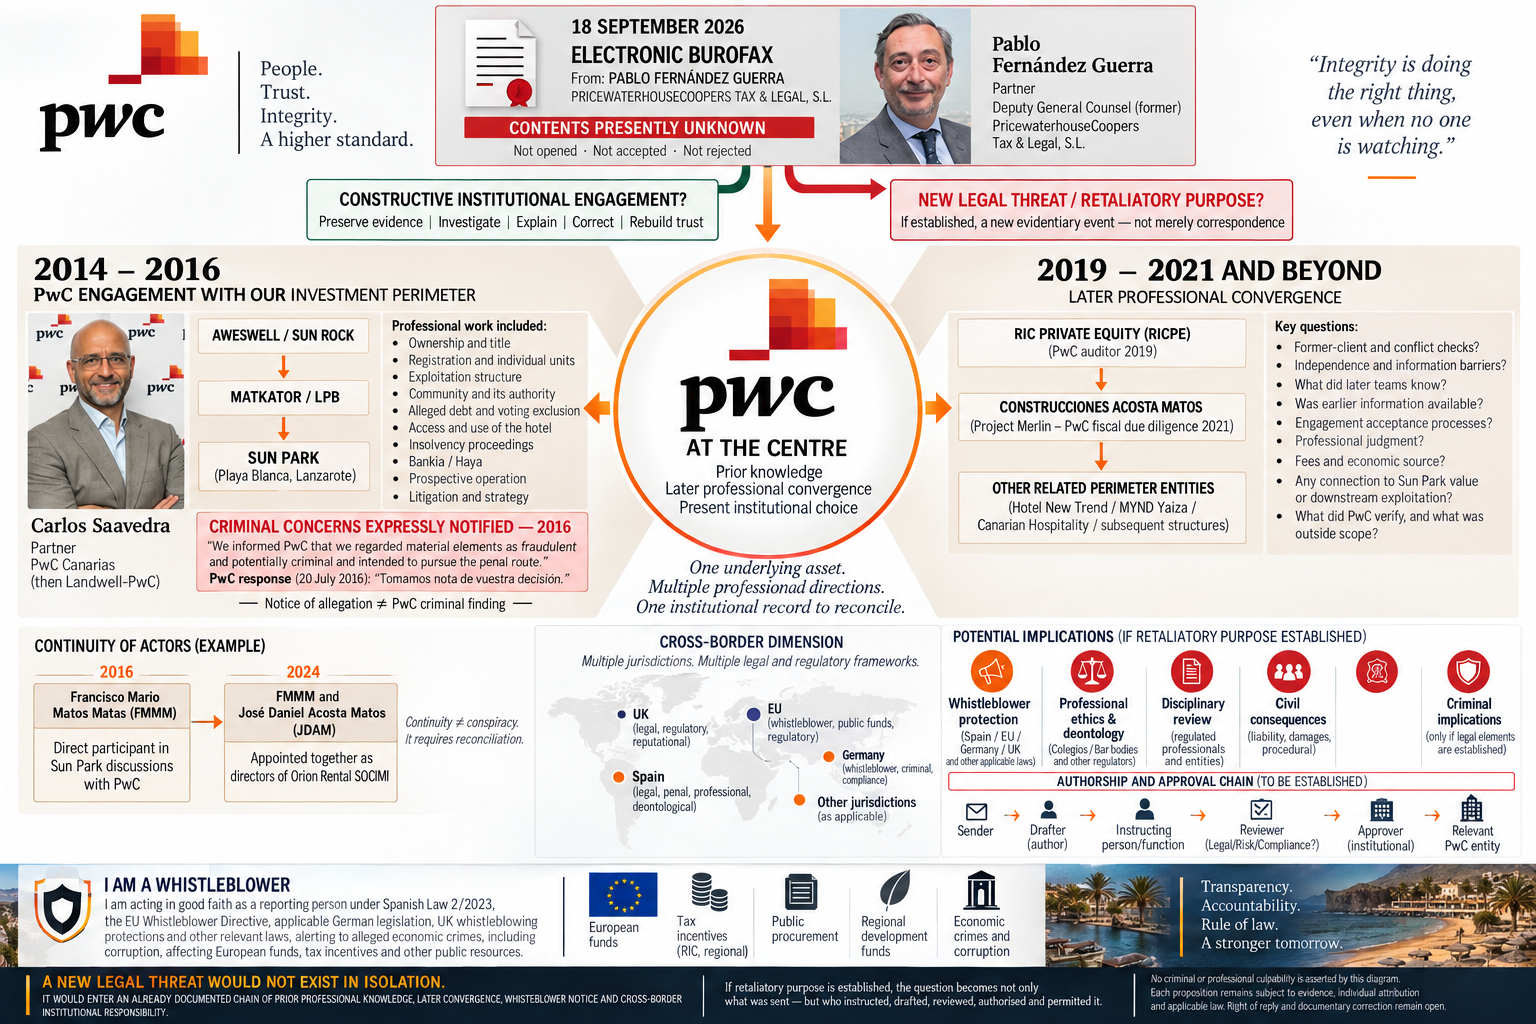
What the fresh notice says
The email asks PwC to treat it as a fresh reporting / whistleblower communication and preservation notice, to the extent the relevant statutory regimes are engaged. Gil Marer states that he is reporting in good faith alleged economic crime and corruption potentially affecting European funds, tax incentives, regional incentives, public support and associated investment structures. That is the reporting capacity asserted in the communication; this page does not transform it into an adjudicated legal status.
The notice makes the traceability point that, after receipt, any later affirmative PwC decision to re-notify, reissue, pursue or insist upon the communication would be a separately identifiable institutional act. Any legal, professional or regulatory significance would depend on the actual document, purpose, actors, evidence and applicable law.
Legal framework and scope — Spain / EU / Germany / UK (full analysis)
Anti-retaliation frameworks raised — applicability remains a legal question
| Framework | Rule raised | Boundary |
|---|---|---|
| Spain · Ley 2/2023 | Article 36 prohibits retaliation and addresses threats and attempts of retaliation against qualifying reporting persons. BOE. | Personal and material scope must be satisfied. The unread burofax is not classified here as retaliation. |
| EU · Directive (EU) 2019/1937 | Article 19 requires prohibition of forms of retaliation, including threats and attempts, for persons within scope. EUR-Lex. | The Directive has its own work-related personal and material scope. |
| Germany · HinSchG | §36 prohibits reprisals and threats/attempts and contains a presumption mechanism in defined occupational-disadvantage circumstances. Official text. | Application depends on the required territorial, personal, material and work-related nexus. |
| UK · PIDA / Employment Rights Act | UK whistleblowing law protects qualifying workers/disclosures against detriment within its statutory framework. Official legislation. | It is not asserted to govern this PwC relationship automatically; statutory status and disclosure tests must be met. |
Precision control. The notice does not establish that Spanish, EU, German and UK protections all apply to the same act, person or relationship. Nor does it say that the unread burofax is retaliatory. It records that PwC was placed on fresh notice of the reporting position and possible cross-border implications before any later institutional decision to take a fresh affirmative step.
Professional / deontological and responsibility-chain questions
If a later communication were actually shown on evidence to be an improper retaliatory escalation, the notice states that review could extend beyond the signature to who instructed, drafted, reviewed and authorised it; what evidence was considered; what former-client/conflict issues were checked; and whether Legal, Risk or Compliance reviewed the step. Where regulated lawyers were involved, applicable professional and deontological duties could require examination by reference to their actual professional status and regulator.
No disciplinary, civil or criminal liability is asserted merely from the notification. Any such consequence would require the relevant factual and legal elements to be established individually.
Cross-border / jurisdiction reservation
The notice was sent for and on behalf of Aweswell Limited, described as the UK holding company and foreign investor in Spain, and by Gil Marer in his asserted reporting-person / whistleblower capacity. It expressly says that requesting authentication, receiving a communication or engaging in discussion is not intended to constitute acceptance of service, submission to Spanish jurisdiction, waiver of forum/service objections, or agreement that any new dispute must be determined in Spain.
Status · 18 September 2026: electronic notification received; burofax contents not retrieved when the fresh notice was sent; reporting/preservation communication sent and verified in the sender's mailbox; institutional map sent with it; PwC's right of reply, correction and documentary explanation remains fully open.
12 · INSTITUTIONAL DOCUMENTARY POSITION · 18 SEPTEMBER 2026
PwC now has a finite documentary route to confirm, narrow or correct the reconstruction.
This is not a finding of wrongdoing. It follows from the documented chronology: prior professional knowledge, later professional convergence, the 2021 Legal/Risk escalation and the fresh 18 September reporting/preservation notice.
THE INSTITUTIONAL TEST
PwC is invited to answer through the established institutional correspondence, not to litigate the record through publicity.
- whether a later PwC team received incomplete or misleading information;
- which former-client, conflict, independence and information-barrier controls operated;
- whether any later engagement was connected to Sun Park itself or was confined to other assets/projects;
- whether any later professional remuneration can be connected to Sun Park value or whether the records exclude that proposition; and
- which primary evidence corrects any factual part of this reconstruction.
Traceability point. From receipt of the fresh notice, any later affirmative institutional step concerning the notified subject matter is separately identifiable in time. That does not make the step improper; it allows purpose, instruction, review, authorisation and evidence to be assessed against the notice and historic record.
Silence is not an admission. Evidence is the test. Documentary corrections, mandate boundaries, conflict records, information-barrier evidence, innocent explanations and primary material may be supplied privately through the existing institutional channel. Material corrections will be reflected publicly with equivalent prominence.
RIGHT OF REPLY · CORRECTION · EQUIVALENT PROMINENCE
PwC, Carlos Saavedra and each named professional are invited to correct this record.
Any documentary correction, engagement-scope clarification, conflict explanation, innocent account or substantive response will be incorporated with equivalent prominence. Non-response will be recorded only as non-response and will not be treated as an admission.
The objective is an auditable reconciliation: what PwC/Carlos knew, what the client instructed, what later Acosta/RICPE work existed on Sun Park or other assets, what conflict controls were applied, why Carlos's calificación evidence was not heard, and what evidence changes the analysis.
Cuatrecasas–RAUDA: from mandate to recovery and remate
One connected factual inquiry with distinct criminal, civil, professional-discipline and recovery tests. Includes the 2022 recovery correspondence, 3 September pleading and July provisional dismissal; no assignment, guilt or stay is presumed. Read the sources, countercase and outstanding evidence.
14–21 SEPTEMBER 2026 · R33 · PWC AS EVIDENCE CUSTODIAN
The AC filing makes the 2016 production question more concrete.
The filing itself reproduces the 29 April 2016 communication raising the Community-debt, arrears, accounting and cost-reconciliation dispute. PwC’s 2016 file can confirm, narrow or rebut parts of that reconstruction without PwC adopting any criminal allegation.
LOCKED CONTROL · 18 OCTOBER 2026 · UK FAILURE-TO-PREVENT-FRAUD REVIEW
From knowledge to economic fruits: what PwC UK must test, not assume.
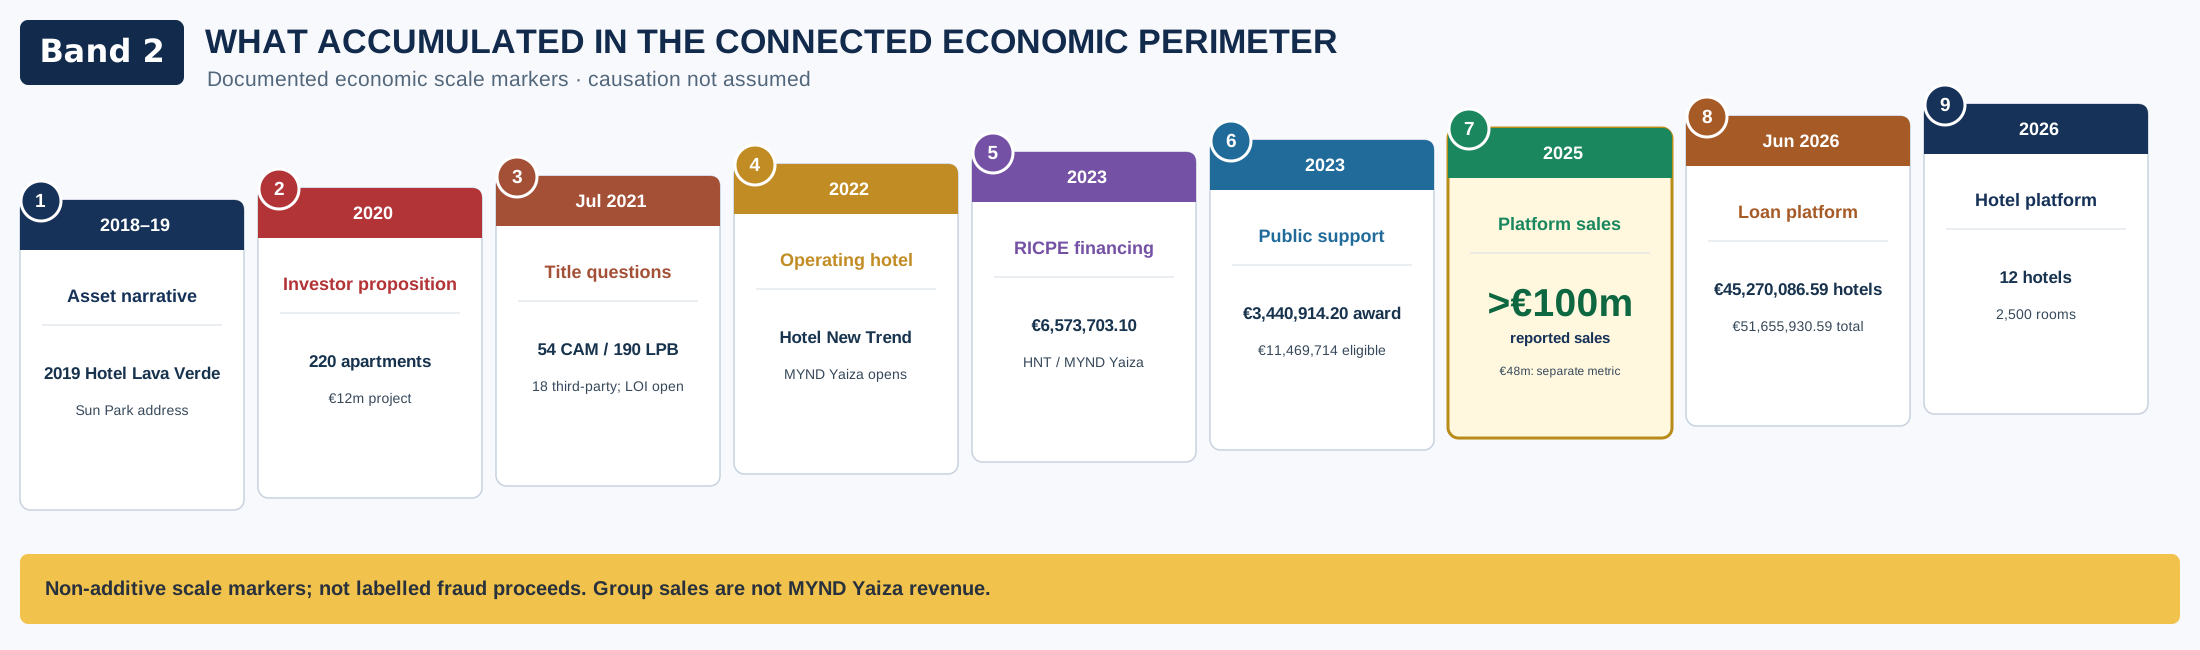
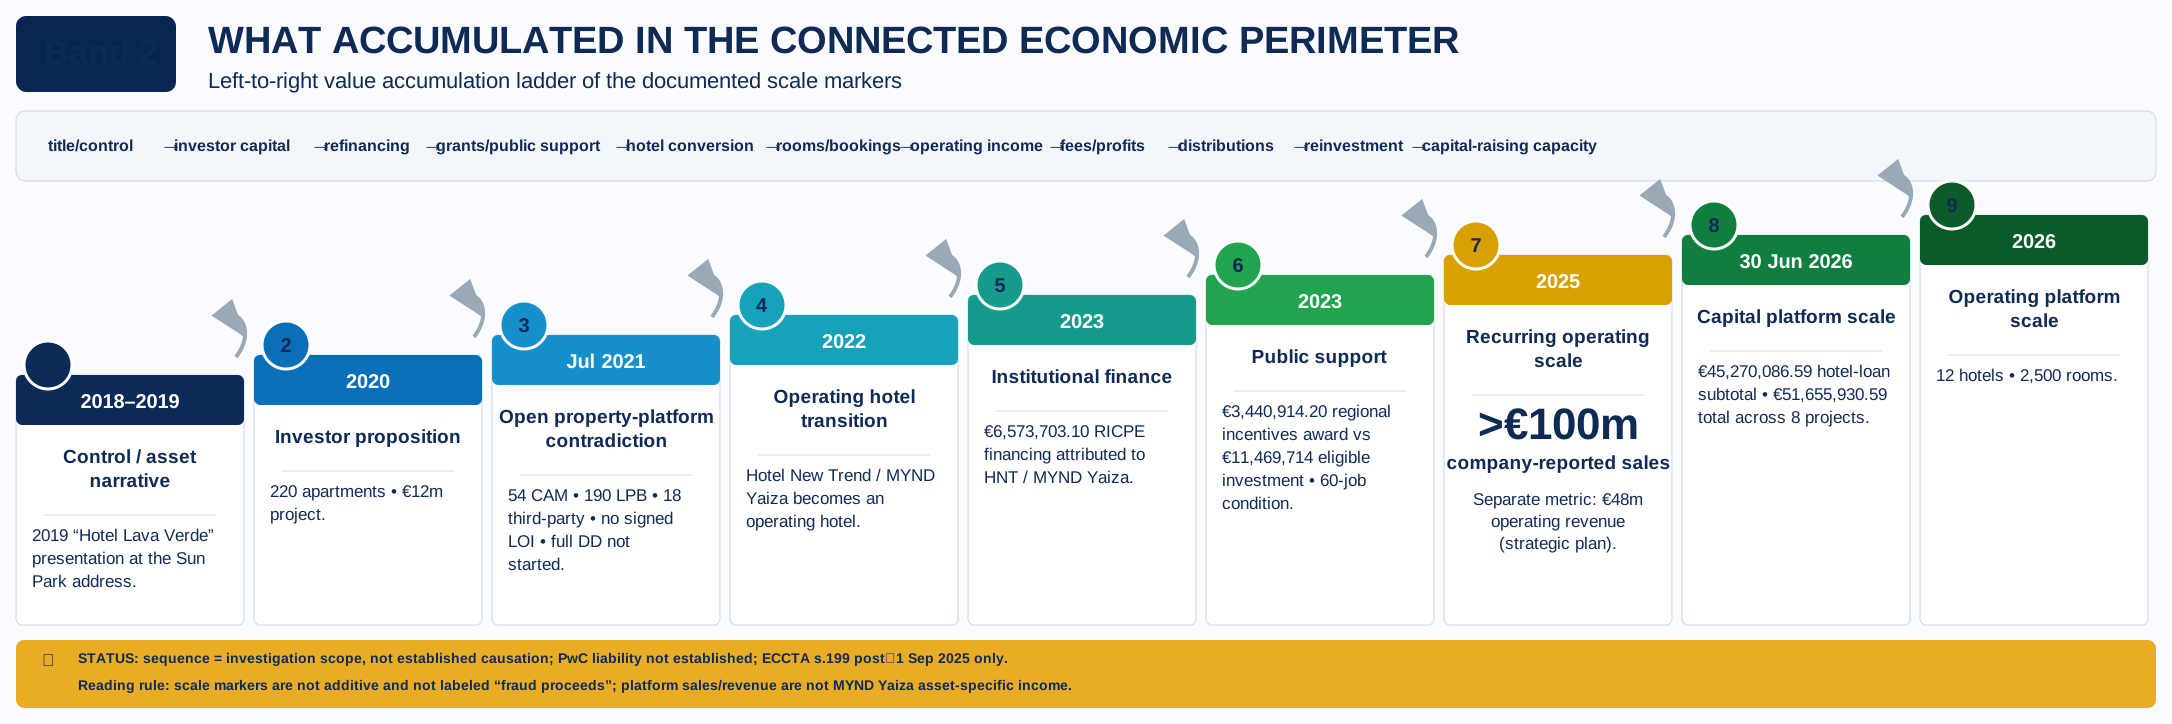
The review question is causal and economic, not rhetorical. The documentary record permits three layers to be placed side by side: what PwC knew or received; the prevention, escalation, conflict, independence and information-governance decisions that remain to be produced; and the asset, finance and operating-value accumulation that followed within the connected Acosta Matos / RICPE perimeter.
Boundary: this section does not state that the figures below are fraud proceeds, that PwC caused the later platform, that every later Acosta Matos asset derives from Sun Park, or that the UK offence applies retrospectively. Causation, associated-person status, the underlying fraud offence, intended benefit, UK nexus and reasonable prevention procedures each require separate proof.
1 · KNOWLEDGE / CONTROL POINTS2014–2016 Sun Park professional record
PwC / Landwell worked on ownership, Community governance, debt, insolvency, litigation and strategy. In June–July 2016 the client directed the response toward the penal route; PwC recorded that the decision was noted. Surviving September 2016 correspondence records direct contact with the Insolvency Administrator.
PwC / Landwell worked on ownership, Community governance, debt, insolvency, litigation and strategy. In June–July 2016 the client directed the response toward the penal route; PwC recorded that the decision was noted. Surviving September 2016 correspondence records direct contact with the Insolvency Administrator.
2 · LATER PWC PERIMETER2019–2021 RICPE / CAM overlap
PricewaterhouseCoopers Auditores, S.L. appears as RICPE auditor for FY2019. RICPE investor material later carried Sun Park. A 2021 RICPE report states that PwC began fiscal due diligence for Construcciones Acosta Matos on another project. These are separate entities and mandates; the information bridge remains to be proved.
PricewaterhouseCoopers Auditores, S.L. appears as RICPE auditor for FY2019. RICPE investor material later carried Sun Park. A 2021 RICPE report states that PwC began fiscal due diligence for Construcciones Acosta Matos on another project. These are separate entities and mandates; the information bridge remains to be proved.
3 · INSTITUTIONAL NOTICEUK Risk → Spain Legal / Compliance
In March 2021 the Sun Park / RICPE concerns were transmitted into PwC UK Legal/Risk and then into a PwC Spain Legal/Compliance channel. The exact PwC entities, office capacities and internal routing remain to be reconciled; transmission to a channel does not by itself prove personal receipt or examination by every named individual. The unresolved issue is what checks, access reviews, conflict searches, barriers, recusals, engagement screening or remedial decisions followed.
In March 2021 the Sun Park / RICPE concerns were transmitted into PwC UK Legal/Risk and then into a PwC Spain Legal/Compliance channel. The exact PwC entities, office capacities and internal routing remain to be reconciled; transmission to a channel does not by itself prove personal receipt or examination by every named individual. The unresolved issue is what checks, access reviews, conflict searches, barriers, recusals, engagement screening or remedial decisions followed.
Economic accumulation markers in the connected perimeter
| Stage | Documentary marker | Economic meaning | Control / evidential boundary |
|---|---|---|---|
| 2018–2019 | Material-control chronology; preserved 2019 “Hotel Lava Verde” presentation at the Sun Park address | Commercial position / pre-formalisation asset narrative | Chronology does not itself establish unlawful control or PwC causation. |
| 2020 | Sun Park presented to investors as a 220-apartment, €12m project | Investment proposition and capital-raising narrative | Investor presentation is not proof of whole-property title or actual funding. |
| Jul 2021 | Controlled source describes 54 CAM / 190 LPB / 18 third-party properties, no signed LOI and full due diligence not yet started | Title / availability contradiction still open | Requires property-by-property reconciliation; not proof of intentional deception. |
| 2022 | Hotel New Trend / MYND Yaiza operating-hotel transition; the alleged contribution of the Sun Park economic unit to it is disputed and requires source support | Disputed asset perimeter becomes an operating hotel | Ownership, contribution, licences, operator and third-party rights remain separate questions. |
| 2023 | Audited accounts attribute €6,573,703.10 of RICPE financing to HNT / MYND Yaiza | Institutional finance attached to the operating project | Finance is not profit, revenue or proof of improper funding. |
| 2023 | Regional-incentives award: €3,440,914.20 against €11,469,714.00 eligible investment; 60-job condition | Public-support layer | Award does not by itself prove payment, misuse, double funding or non-compliance. |
| 2025 | Canarian Hospitality strategic-plan reporting: €48m operating revenue; its own site separately reports >€100m sales | Recurring hotel-platform economics | Different reported denominators. Neither figure is treated as MYND Yaiza's asset-specific revenue. |
| 30 Jun 2026 | RICPE valuation: €45,270,086.59 hotel-loan subtotal; €51,655,930.59 total across eight projects | Capital-platform scale | Loan funding, valuation, sales, profit, distributions and recoverable loss must remain separate. |
| 2026 | Canarian Hospitality self-description: 12 hotels / 2,500 rooms | Multi-asset hotel-management / operating platform | Ownership ≠ management ≠ brand ≠ finance. Company-wide inventory is not a Sun Park title finding. |
Economic-fruits inquiry: trace, asset by asset and year by year, title/control → investor capital → refinancing → grants/public support → hotel conversion → rooms/bookings → operating income → fees/profits → distributions → reinvestment → further capital-raising capacity. Identify which increments are independently generated, which are third-party funded, and which—if any—are causally connected to conduct that is ultimately established as fraud.
ASSET / TITLE VALUEHotel/property/control rights, contributions and formalisation.
FINANCE / CAPITAL ACCESSRICPE financing, investor access, refinancing and capital-raising capacity.
PUBLIC SUPPORTRegional incentives / FEDER-connected support, without presuming illegality.
OPERATING FRUITSRooms, bookings, hotel revenue, management income, fees, profits, distributions and reinvestment.
Asset-specific production gap: a sufficiently reliable annual MYND Yaiza revenue / EBITDA / distribution series has not yet been located in the controlled corpus. Group-wide Canarian Hospitality sales or operating-revenue figures must not be substituted for MYND Yaiza's own hotel income. Produce HNT / MYND Yaiza statutory accounts, operator statements, PMS / OTA data, bank receipts, management / lease agreements, fees, EBITDA, distributions and reinvestment schedules.
UK Economic Crime and Corporate Transparency Act 2023 — section 199
The UK failure-to-prevent-fraud offence came into effect on 1 September 2025. Historical PwC events are therefore relevant as knowledge, risk-assessment and governance context; they are not converted retrospectively into the offence. The post-commencement inquiry is whether a specified fraud offence by an associated person, intended to benefit a qualifying organisation or—where the statutory conditions are met—a client for whom services were provided, occurred within the relevant UK nexus, and whether reasonable fraud-prevention procedures were in place.
Post-commencement conduct
Identify any relevant conduct after 1 September 2025 and the exact PwC entity, associated person, client and service relationship.
Underlying offence + benefit
Identify the specified fraud offence said to have occurred and the evidence of the required intention to benefit the organisation or relevant client.
Reasonable procedures
Produce the fraud-risk assessment, due diligence, escalation, conflicts/independence controls, training, monitoring and review relevant to the identified risk.
Independent review
Historical Spain decision-makers should not be the sole arbiters of the adequacy of their own controls. Route the review to an appropriately independent UK / Global Legal, Risk or governance function.
Official UK sources: ECCTA 2023 · section 199 · Home Office failure-to-prevent-fraud guidance. Reading rule: scale markers are not additive and are not labelled as fraud proceeds.
Band 2 — documented economic accumulation
Visual scale markers only: not labelled fraud proceeds, not additive; group sales are not MYND Yaiza hotel revenue.