The file should permit reconstruction of title, valuation, borrower, security, risk, compliance and decision authority.
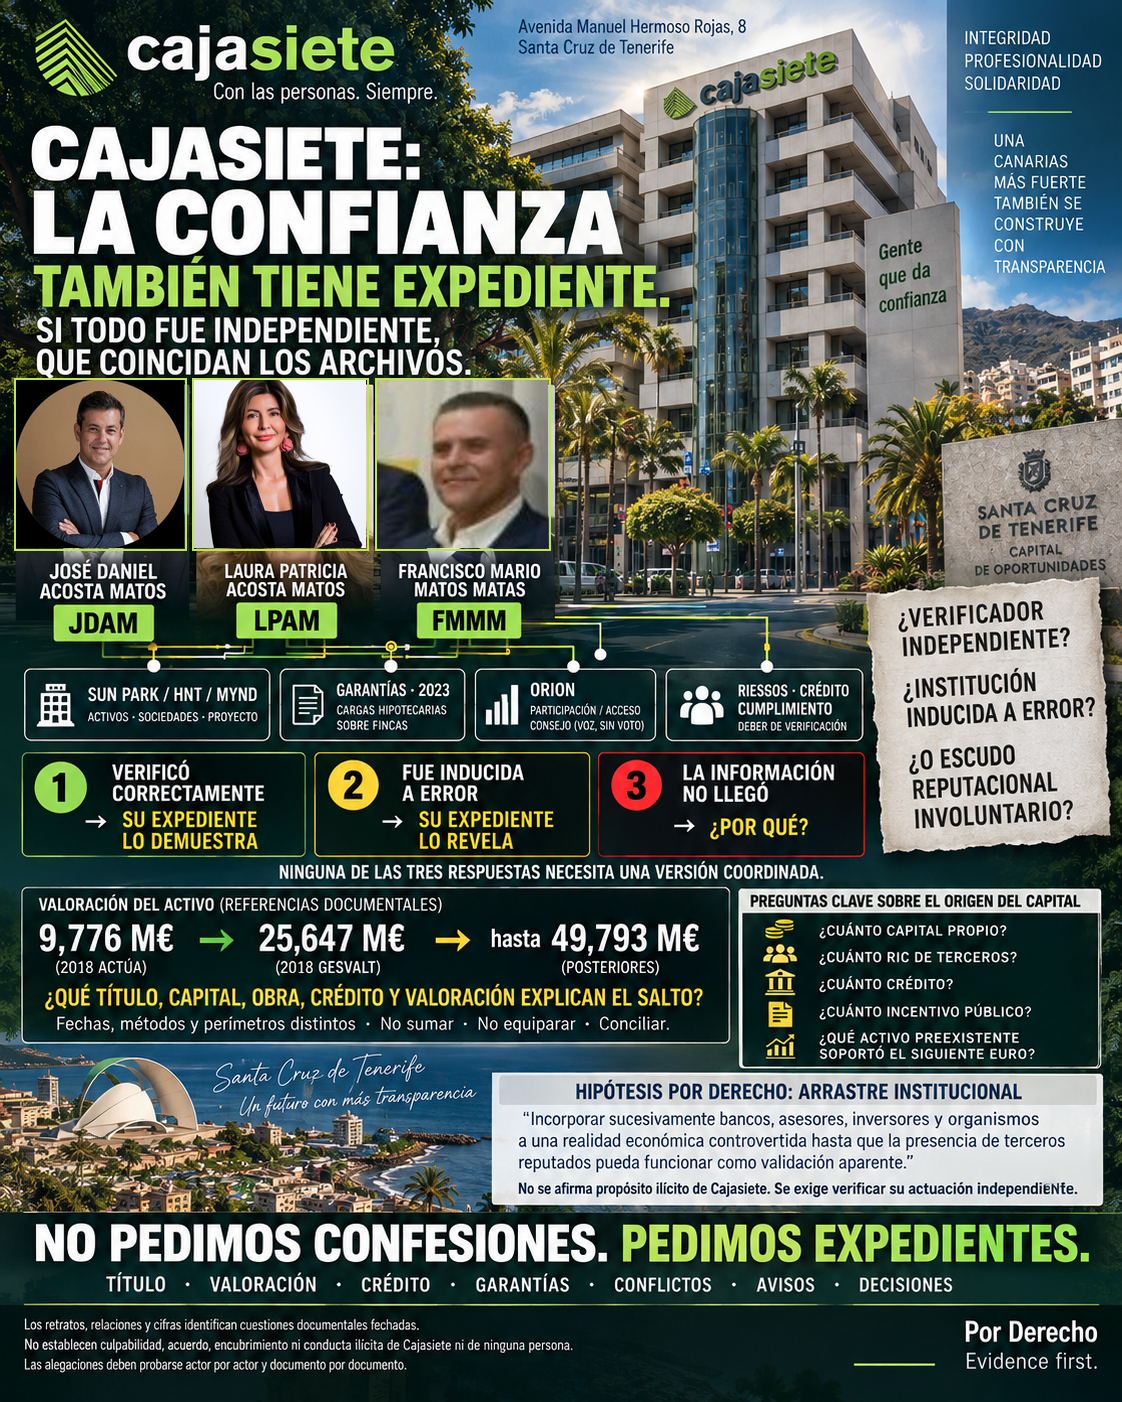
Explanatory/editorial composite. It is not documentary photography of an event or of Cajasiete premises. The three portraits come from the canonical assets identified in the repository.
The file may show what was received, from whom, when, what was missing and which controls were triggered.
The question is then one of traceability: which channel, function and escalation should have applied.
Evidential boundary. This page does not state that Cajasiete knowingly participated in unlawful conduct. The questions are whether it verified independently, received defective or incomplete information, or relevant information failed to reach the functions that should have examined it.
What should be reconcilable
The locales episode, later insolvency decisions and their effects must not be collapsed into later financing.
Title/adjudication chain, segregation into HNT and transformation/operation as MYND Yaiza.
The controlled registry set identifies later Cajasiete security over several former Sun Park units. The controlled examples do not prove how much cash was actually advanced, the complete facility, its valuation or 2018 financing.
At the documented reference dates Cajasiete was recorded with 500,000 ORION RENTAL SOCIMI shares / 5%; that percentage is not carried forward as current without the post-capital-increase register. ORION documentation described a right to attend its board with voice but without vote. Later ORION governance roles of FMMM and JDAM, and LPAM's CAM/Sun Park chain, remain distinct by capacity and date. RICPE identifying both MYND Yaiza and ORION as financed projects does not by itself establish a transfer, shared security or cash-flow bridge between the branches.
Three figures that must not be collapsed
€9.776m → €25.647m → up to €49.793m
Different dates · perimeters · methodologies. Do not add. Do not equate. Reconcile.
ACTÚA (January 2018, ≈€9.776m), GESVALT (May / 7 June 2018, ≈€25.647m) and later RPE/DCF bases (up to ≈€49.793m) are not mechanically equivalent figures.
WHAT TITLE, CAPITAL, WORKS, CREDIT, INCENTIVE AND VALUATION EXPLAIN EACH STEP?
HOW MUCH OWN CAPITAL? · HOW MUCH THIRD-PARTY RIC? · HOW MUCH CREDIT? · HOW MUCH PUBLIC INCENTIVE?
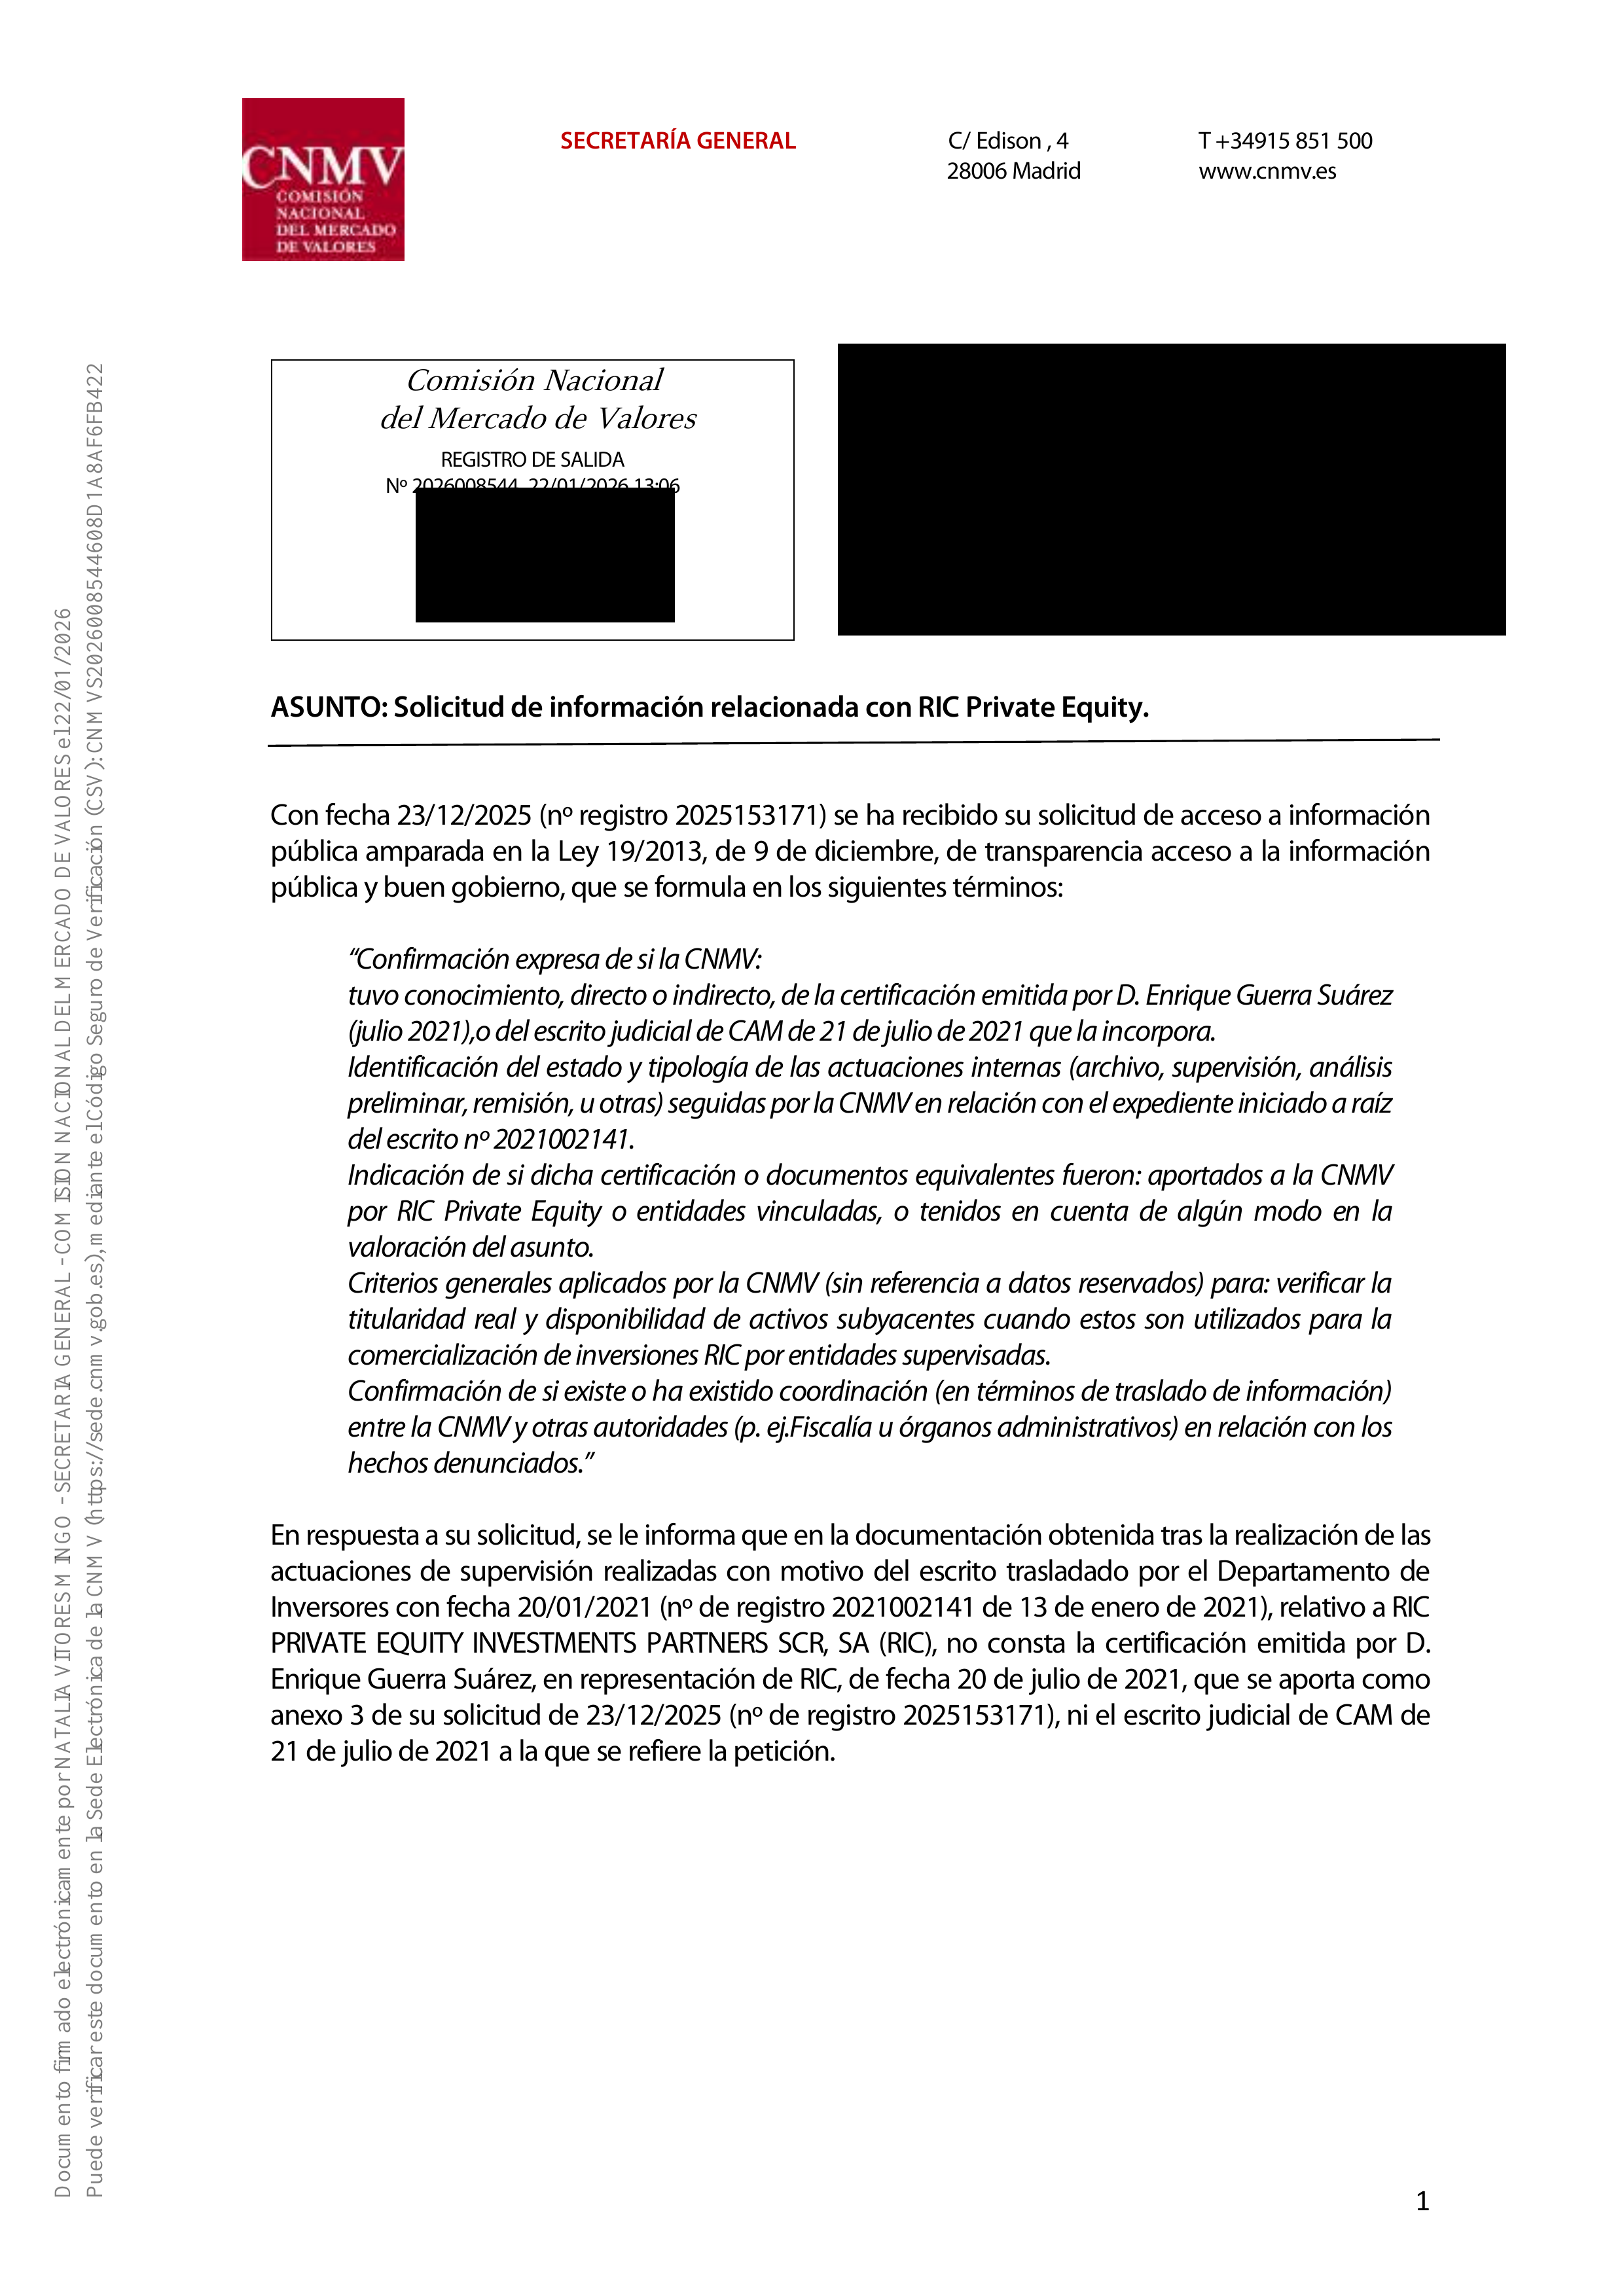
CNMV: two different documents
22 January 2026 · outgoing 2026008544
The Secretary General's response confirms supervisory action concerning RIC Private Equity following the January 2021 communication and says the 20 July 2021 Enrique Guerra certificate and 21 July 2021 CAM court filing were not in the documentation obtained through those supervisory actions. It does not say CNMV found misconduct, contacted PwC, validated a criminal thesis or determined Cajasiete's banking file.
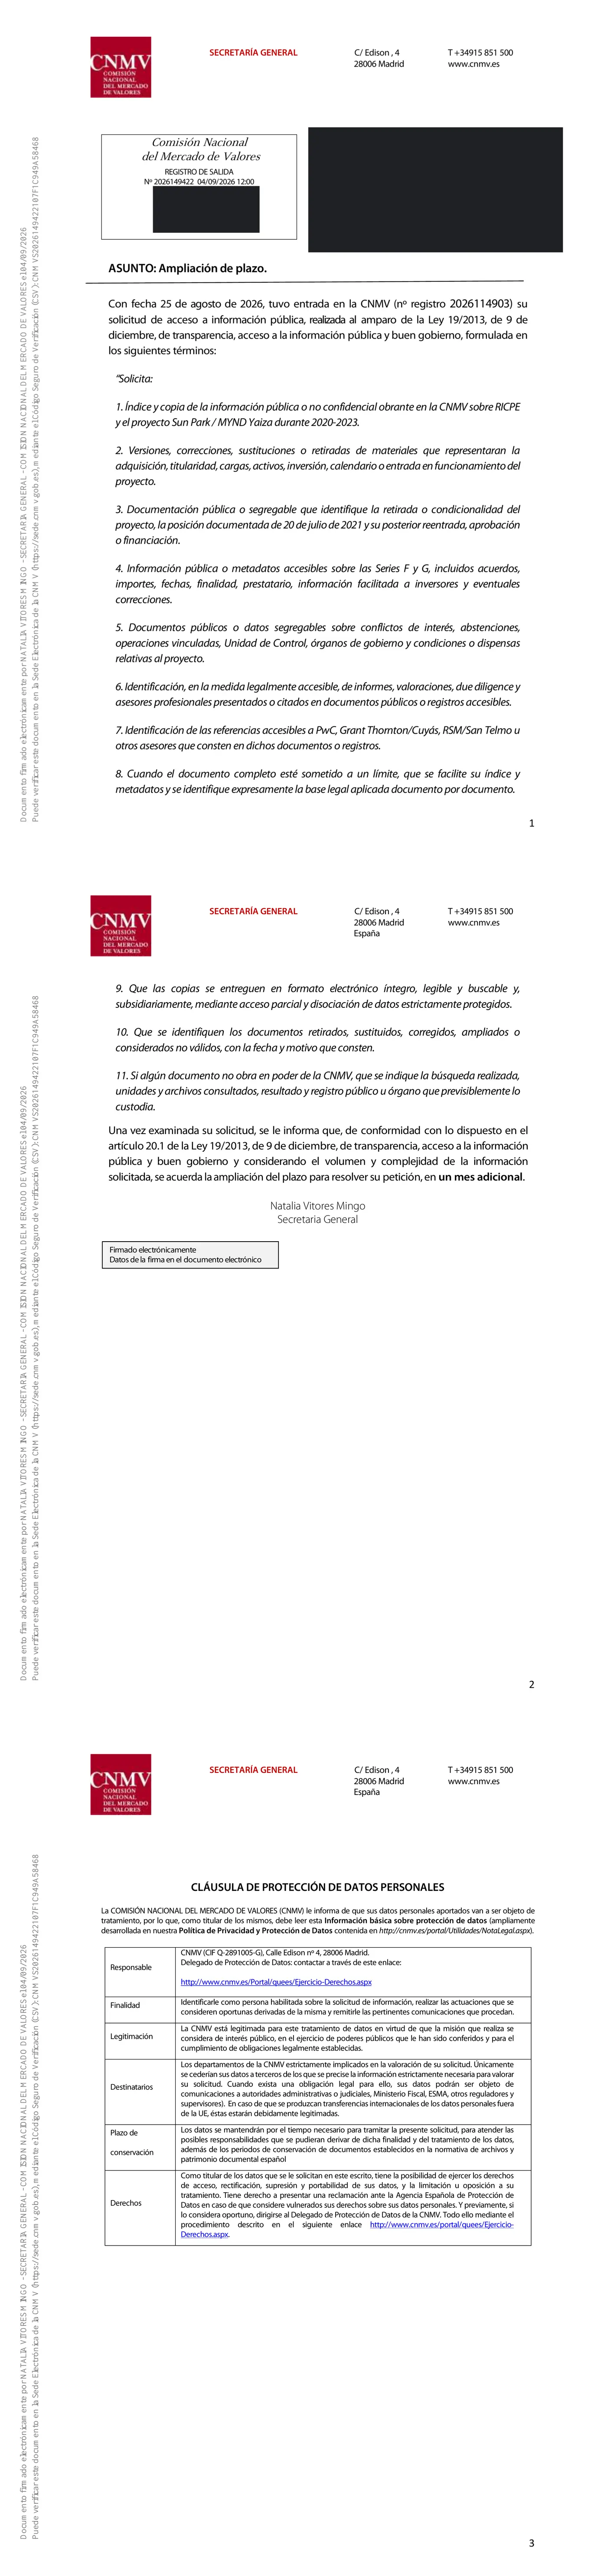
4 September 2026 · outgoing 2026149422
This document grants one additional month to decide the 25 August transparency request because of its volume and complexity. Questions reproduced in it are the applicant's questions, not CNMV findings.
Ethics channel: controlled chronology
Protected-disclosure confirmation request.
Cajasiete replied that it complies with Ley 2/2023 and directed the matter to its ethical channel.
The channel confirmed receipt, communication ID 6.
After preliminary examination, the channel communicated inadmission, citing among its stated grounds public knowledge/rumour, a possible personal dispute external to the organisation, and scope and ability to investigate or remedy; destruction was announced.
The 22 January and 4 September 2026 CNMV documents were supplied to the channel and institutional recipients.
Finite questions for Cajasiete
Who was the borrower? Which facility was approved? What principal was actually drawn? Which units secured it? Which valuation and date were used? What title chain and litigation were disclosed? What KYC/beneficial-ownership and conflict checks were performed? Who decided and what information did they receive? Was there later review after the institutional communications?
WE DO NOT ASK FOR CONFESSIONS. WE ASK FOR RECORDS.